What the autumn forecast says
The Commission published its Autumn 2026 Economic Forecast on 17 November. Euro area GDP growth for 2026 is now put at 1.2%, against 0.9% in the spring round. The wider EU is forecast at 1.4%, up from 1.1%. For 2027 the figures are 1.2% and 1.4%; for 2028, 1.3% and 1.5%.
Inflation is the other half of the document. Euro area inflation is forecast at 3.2% this year and 3.1% next year, before falling to 2.1% in 2028. Across the EU the path is 3.3%, 3.2% and 2.3%. The 2027 figure was revised upward by 0.8 percentage points compared with the spring projection.
Employment growth in the EU is expected to slow to 0.4% in 2026, roughly 800,000 additional jobs. Investment growth slows to 1.5% this year and picks up slightly to 1.6% in 2027.
Growth carried by industrial exports
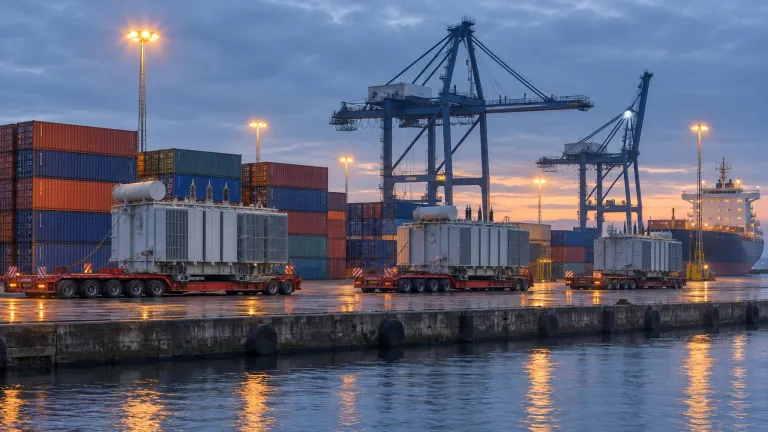
The upward revision is not the result of a sudden consumer boom. According to the Commission, it reflects stronger performance than expected in the first three quarters of 2026, supported by steady household consumption and by an export surge in capital goods feeding the global artificial intelligence and electrification buildout.
In plain terms, that means power equipment, cooling systems and chipmaking machinery. Europe is not where most of the largest AI data centres are being built, but it supplies a good part of what they run on and what is needed to manufacture the chips inside them. When a new cluster of servers is ordered somewhere in the world, a share of the orders lands with European engineering firms, cable makers and transformer plants.
That is a different kind of AI story from the model launches that fill tech headlines. It shows up in factory order books, in port traffic and in the growth statistics, not in a product announcement.
Energy keeps inflation above target
The October numbers explain why the inflation forecast moved the other way. Euro area annual inflation rose from 3.8% in September to 4.0% in October, according to Eurostat's harmonised index. The energy component climbed 20.8% year on year, up from 18.9% a month earlier. Services inflation stood at 3.3%.
A rough calculation shows where the pressure sits. Energy carries about a tenth of the weight in the HICP basket; at 20.8% annual growth, that component alone accounts for roughly two percentage points of the 4.0% headline rate. Strip energy out and the picture looks far closer to normal.
The Commission now expects headline inflation to peak above 4% somewhere between late 2026 and early 2027, rather than sliding smoothly toward 2% as the spring forecast assumed.
The compounding matters more than any single year. At 3.2% in 2026 and 3.1% in 2027, prices rise about 6.4% over two years. Add the 2.1% forecast for 2028 and the cumulative increase over three years comes to roughly 8.6%. A basket of everyday goods that cost €1,000 at the end of 2025 would cost around €1,086 by the end of 2028, even if the annual rate is falling by then.
Borrowers, small firms and the 2% target
The European Central Bank aims for 2% inflation over the medium term. A forecast that keeps the rate above 3% through 2027 describes a third consecutive year in which prices outrun that target, which is not the backdrop borrowers hoped for when they were told the inflation shock of 2022 and 2023 would pass.
The Commission's forecast does not set interest rates. The ECB does, and it publishes its own projections. Still, households with variable-rate mortgages and small firms rolling over business loans watch these documents because they shape the debate around how fast rates can come down.
For a small manufacturer the arithmetic is blunt. Energy is an input cost before it is a headline. A bakery, a print shop or a metal workshop paying more for electricity in October 2026 than in October 2025 has less room to absorb higher rents or wages, and the growth revision in Brussels does not appear on its invoice.
The forecast also carries a lesson about the AI economy that is easy to miss. The same buildout lifting Europe's export numbers is electricity-hungry. Europe earns from supplying the equipment; it also competes for the power that equipment needs, alongside households and industry. The Commission's own numbers put those two effects side by side, without pretending they cancel out.
The full forecasts are published on the Commission's economic forecasts pages.
Why are there two sets of numbers, one for the euro area and one for the EU?
The euro area covers only the countries that use the euro. The EU figure includes the member states outside the currency union, which is why the two differ: EU growth is forecast at 1.4% for 2026 against 1.2% for the euro area, and EU inflation at 3.3% against 3.2%.
Does this forecast decide what I pay on my mortgage?
No. The European Central Bank sets interest rates and produces its own projections. The Commission's forecast is one of the documents markets and commentators read when discussing the rate path, but it has no direct effect on lending conditions.
What is HICP and why does it matter?
The Harmonised Index of Consumer Prices is the inflation measure Eurostat compiles so that price changes can be compared across EU countries on the same basis. The 4.0% figure for October 2026 is an HICP number, and it is the one the Commission uses for its forecasts.